Blog
Blog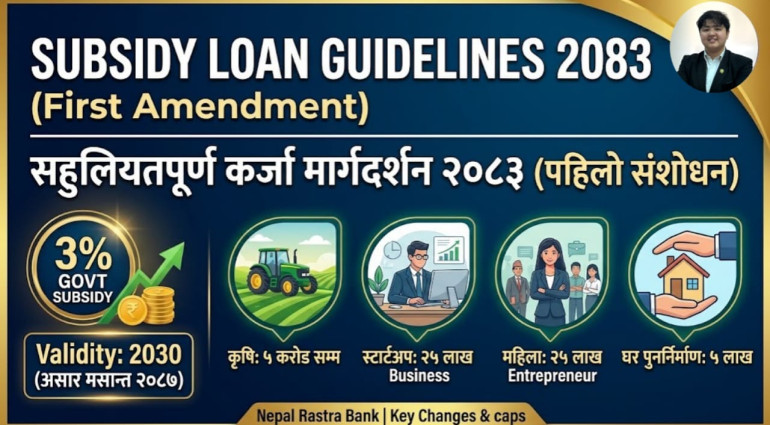
Subsidy Loan Guidelines (First Amendment), 2083 / सहुलियतपूर्ण कर्जाका लागि ब्याज अनुदानसम्बन्धी (पहिलो संशोधन) कार्यविधि, २०८३
Nepal Rastra Bank (NRB) issued a notice enforcing the First Amendment to the Interest Subsidy Guidelines for Subsidized Loans (First Amendment), 2083 under Section 79 of the NRB Act, 2058. Grounded in Section 65(4) of the Financial Procedures and Fiscal Accountability Act, 2076 (आर्थिक कार्यविधि तथा वित्तीय उत्तरदायित्व ऐन, २०७६), this framework aims to promote entrepreneurship, modernize traditional skills, and support housing reconstruction for natural disaster victims through subsidized interest, credit guarantee, and insurance coverage.
a. Key Loan Schemes & Credit Caps
Lenders (Class “A”, “B”, “C”, and “D” BFIs) can extend collateral or group-guarantee loans under the following limits:
|
Agriculture & Livestock Loan |
Up to NPR 5 Crore. |
|
Boiler Replacement Loan for Industries |
Up to NPR 50 Lakhs. |
|
Women Entrepreneurship Loan |
Up to NPR 25 Lakhs. |
|
Startup Enterprise Loan |
Up to NPR 25 Lakhs. |
|
Youth Returnee Employment Loan (Foreign Employment for that Nepali citizen who has worked abroad for at least 6 months with an approved labor permit) |
Up to NPR 20 Lakhs. |
|
Educated Youth Project Loan |
Up to NPR 20 Lakhs. |
|
Dalit Community Bhagat Sarvajit Enterprise Loan |
Up to NPR 20 Lakhs. |
|
Disaster Victim Private Housing Loan |
Up to NPR 5 Lakhs. |
| Gen-Z Movement Martyrs' Families and Injured Targeted Self-Employment Enterprise Loan | Up to 15 Lakhs (Enacted via Amendment on 2083/04/22) |
b. Interest Rates, Subsidies & Fees
- Interest Rate Cap: Lenders are restricted to charging a maximum markup of Base Rate + 1.5%.
- Interest Subsidy Rate: The Nepal Government provides a 3% interest subsidy on applicable loan interest rates after the applicable loan, interest and insurance premium is deposited.
- Subsidy Duration: Up to a maximum of 5 years.
- Validity Period: Subsidized loans under this scheme can be granted up to Mid-July 2030 (असार मसान्त २०८७).
c. Credit Guarantee & Insurance Sharing (Up to NPR 15 Lakhs)
i. Credit Guarantee Fee: 50% paid by the BFI, 50% reimbursed by the Government via NRB.
ii. Insurance Premium: 50% paid by the borrower, 50% reimbursed by the Government via Nepal Insurance Authority.
Note: For loans exceeding NPR 15 Lakhs, full guarantee fees are borne by BFIs and insurance premiums by borrowers.
d. Eligibility Highlights & Key Restrictions
- General Eligibility: Must be a Nepali citizen, at least 18 years old, possess a PAN, not be blacklisted, and not be recommended for action under Section 23 of the guidelines. For entity-based loans, the enterprise/firm must be 100% Nepali-owned and registered under prevailing law. Special Eligibility for Gen-Z Movement Beneficiaries (Added 2083/04/22) Under the new amendment, applicants for the Gen-Z Self-Employment Loan must submit official certification from the Government of Nepal or a designated authority verifying their status as an an injured participant of the Gen-Z movement or a family member of a martyr of the Gen-Z movement. For the purpose of this provision, a "Martyr's Family" is strictly defined as the martyr's spouse (husband/wife), son, daughter, father, or mother.
- One-Family, One-Loan Rule: Only one family member across an undivided family is eligible for a subsidized loan.
- Foreign Permanent Residency Bar: Individuals holding permanent residency status (PR/EDV) in any foreign country are strictly ineligible.
- No Loan Swapping: Transferring a subsidized loan from one BFI to another results in the automatic cancellation of the interest subsidy.
- Disaster Victim Housing Restriction: Applicants who have already received housing construction grants from the National Disaster Risk Reduction and Management Authority (NDRRMA) or other institutional sources are ineligible for a subsidized private housing loan.
e. Loan Approval Timelines
- Decision Window: BFIs must evaluate and decide on a loan application within 15 working days.
- Rejection Notice: If an application is rejected, the BFI must issue a written statement outlining the specific grounds and reasons within 3 working days.
Summary Table
|
Feature |
Key Provision |
|
Government Interest Subsidy |
3% direct subsidy |
|
Maximum Lending Rate |
Base Rate + 1.5% (No additional hidden fees allowed) |
|
Maximum Subsidy Period |
5 Years |
|
Application Approval SLA |
15 Working Days |
|
Scheme Termination Date |
Mid-July 2030 (असार मसान्त २०८७) |
Planning to Access Subsidized Enterprise Financing?
Whether you are structuring a Women Entrepreneurship Loan, Startup Enterprise Loan, or Agriculture & Livestock financing under the updated 2083 Guidelines, navigating NRB compliance, single-family limits, and BFI documentation requires strategic legal foresight. Ensure your business meets all legal requirements and secures maximum funding eligibility. Contact Advocate Sahara Sharma today to schedule a professional consultation.
Disclaimer: The content of this article is for informational and educational purposes only and does not constitute formal legal advice. Contacting the author via the details above does not automatically create an advocate-client relationship.